
More NOI for your mission.
Explore solar, storage and EV charging for lower operating costs, with ownership and funding options reviewed before you commit.
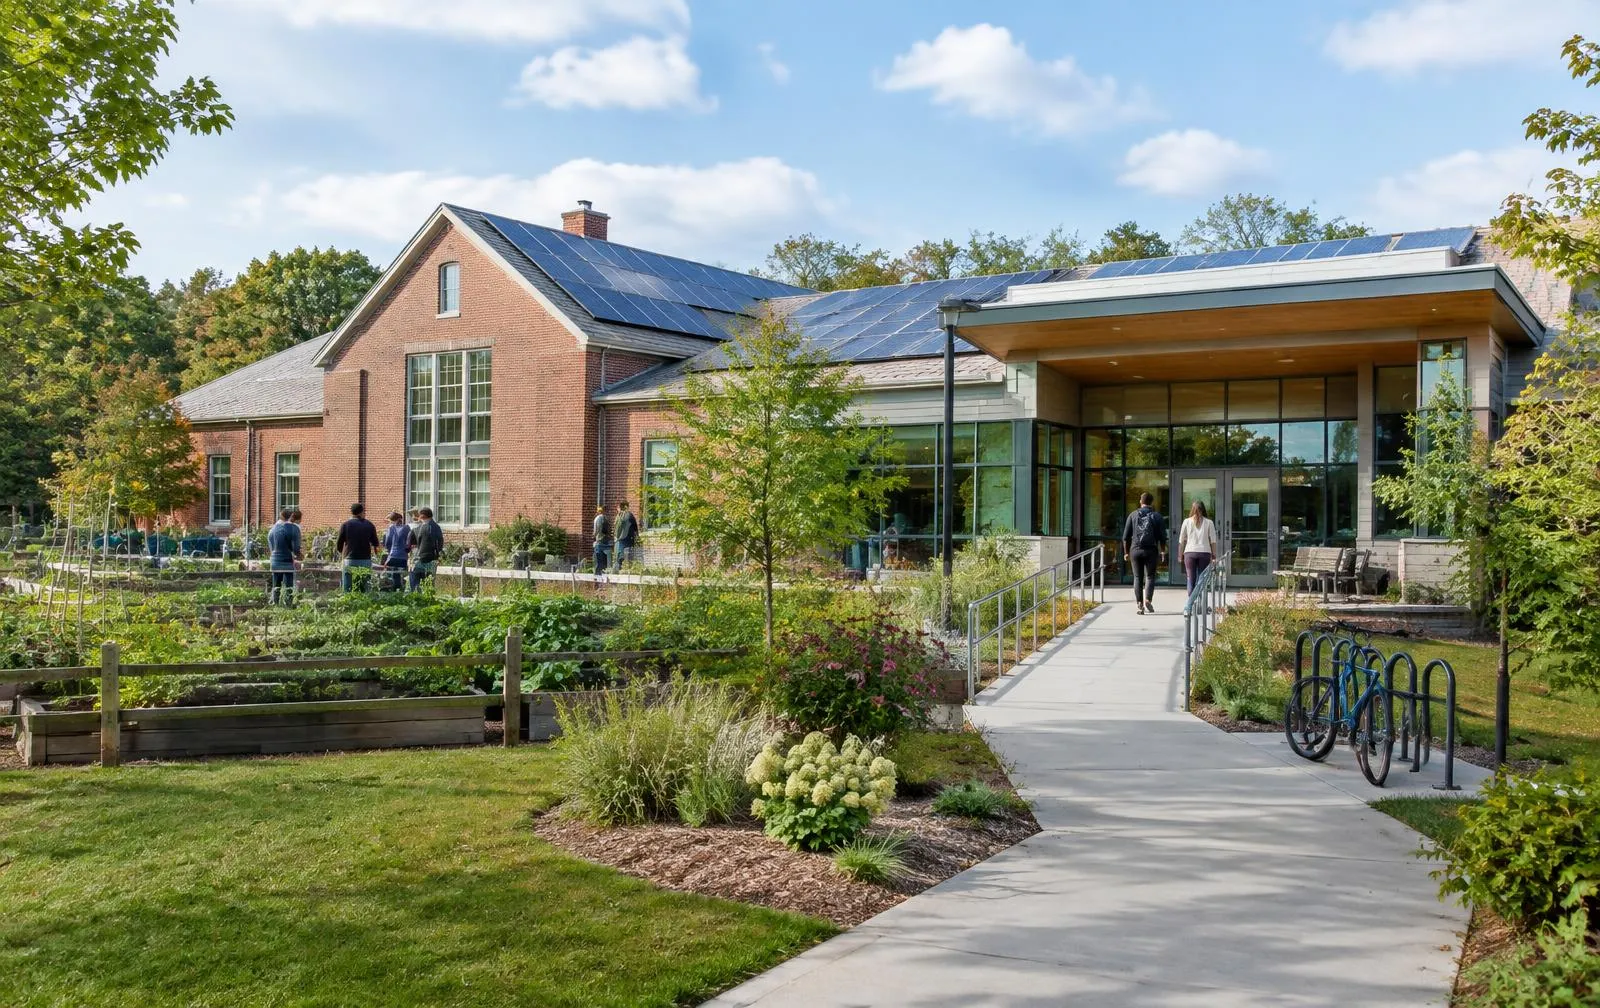
Why this segment fits
For houses of worship, private K-12 schools, community centers, faith-based social services and diocesan portfolios. Eligible tax-exempt entities may use elective pay when they own qualifying assets and meet the credit requirements; third-party ownership follows a different tax structure, confirmed with your advisers.
No usable tax credit
Tax-exempt owners cannot use a credit against tax; elective pay applies where the organisation owns the qualifying asset and meets the requirements.
No capital budget
Capital campaigns compete with programs, so funding options that need little or no upfront capital matter.
Multi-site portfolios
Dioceses and school networks contract once and roll out site by site.
How a project is structured.
NOI coordinates design, funding, construction and operation of the on-site solar, battery and EV assets, working with licensed installers and engineers.
Who funds the project, who owns the equipment and how the benefit is shared depend on the structure chosen for that project — owner-funded, financed, or third-party funded — and are set in the project agreement after underwriting. Where a funding partner owns the system, the owner typically hosts it under an agreement and either buys energy on site or receives a payment. Tax credits, depreciation and state incentives are assessed per project against the owner’s own tax position; confirm treatment with your tax advisors.
- 01Start with utility bills and available site information.
- 02Screen tariff, load and funding options; confirm whether a deeper assessment fits.
- 03If viable, arrange site, structural and electrical reviews; timing depends on access and scope.
- 04Present a proposal with assumptions, ownership terms and any verified incentive or compliance eligibility.
- 05Agree contracts and pursue required owner, lender, permit and utility approvals.
- 06Schedule construction and commissioning once approvals and interconnection requirements are clear.
Four forces shaping the non-profit decision
Regulatory pressures and rate structures reshaping the Northeast energy decision for this segment. Confirm current statute specifics with your tax and legal advisors.
Available where the organisation owns the qualifying asset and meets the credit requirements.
Owner-funded, financed or third-party funded; costs, charges and maintenance are set in the project agreement.
Multi-site master agreements across a network or diocese.
State incentive programs stack where the site and owner qualify.
Eligible tax-exempt and public entities may use elective pay when they own qualifying clean-energy assets and meet the credit requirements. Third-party ownership follows a different tax structure. We compare ownership and funding options with the institution and its tax advisers before presenting project economics. Primary source: IRS — elective pay and transferability FAQs.
Learn more →Rates we work with
- ConEd SC-9 Rate III
- PSE&G BPL / GLP
- Eversource G3 / G4
- National Grid SC-2 / SC-3
- PSEG-LI 285 / 281
- JCP&L GS-Secondary
- United Illuminating GS-3
- PECO GS-Medium
Each has its own peak-hour, demand-charge and TOU structure. Our model reads your specific tariff.
Not-for-Profit: NOI compared with an ESCO retrofit
| Dimension | Typical ESCO retrofit | An NOI project |
|---|---|---|
| Who funds it | Owner capital, a bond issue or ESCO-arranged debt, per the contract | Owner-funded, financed or third-party funded — chosen per project |
| Equipment ownership | Usually the owner once installed | The owner or a funding partner, as set in the project agreement |
| Tax credits and depreciation | Depends on the owner's tax position | Assessed per project; direct pay considered where a tax-exempt owner is eligible |
| Long-term O&M | Scoped inside the performance contract | Coordinated by NOI under the operating scope agreed |
| Scope | Often a bundled retrofit across building systems | The solar, storage and EV assets |
| Decision path | Procurement, board or bond process | A review first, then a project agreement |
| Savings treatment | Frequently framed as guaranteed savings | Modeled and stated with assumptions; no savings guarantee |
The fastest path is a modeled number on your specific building.
Send us the property details. You get a written initial review within 2 business days, with the assumptions stated.
You may also be looking for
Higher Education
Campus energy and ownership options
Learn more →Public Sector
Operating-budget savings and reliable power
Learn more →HOA & Condo
Common-area costs, options without an assessment
Learn more →How the energy adds to your NOI, in plain English: How owners earn · Check your building in 60 seconds
All figures on this page are directional. Every deal is modeled to your specific tariff, load and roof. Incentive claims reflect our understanding as of the page date and require confirmation with tax and legal advisors before signature.